
How to calculate your net worth and why the liquid number matters
Net worth is the simplest measure of where you stand with money. Add up everything you own, subtract everything you owe, and the result is your net worth. But that single number hides an important detail. This article walks through the calculator, explains each field, and shows why the liquid figure deserves just as much attention.
The basic idea behind net worth
Net worth is total assets minus total debts. If you own things worth three hundred thousand and owe one hundred and ninety thousand, your net worth is one hundred and ten thousand. The number can be positive, negative or zero. A new homeowner who just took out a mortgage is very likely negative, and that is perfectly normal.
What makes net worth useful is that it captures your whole financial picture in one figure. Income alone does not do this because it says nothing about what you owe. Savings alone does not do it because it ignores property and pensions. Net worth pulls everything together, and watching it over time tells you whether things are moving in the right direction.
Filling in the asset fields
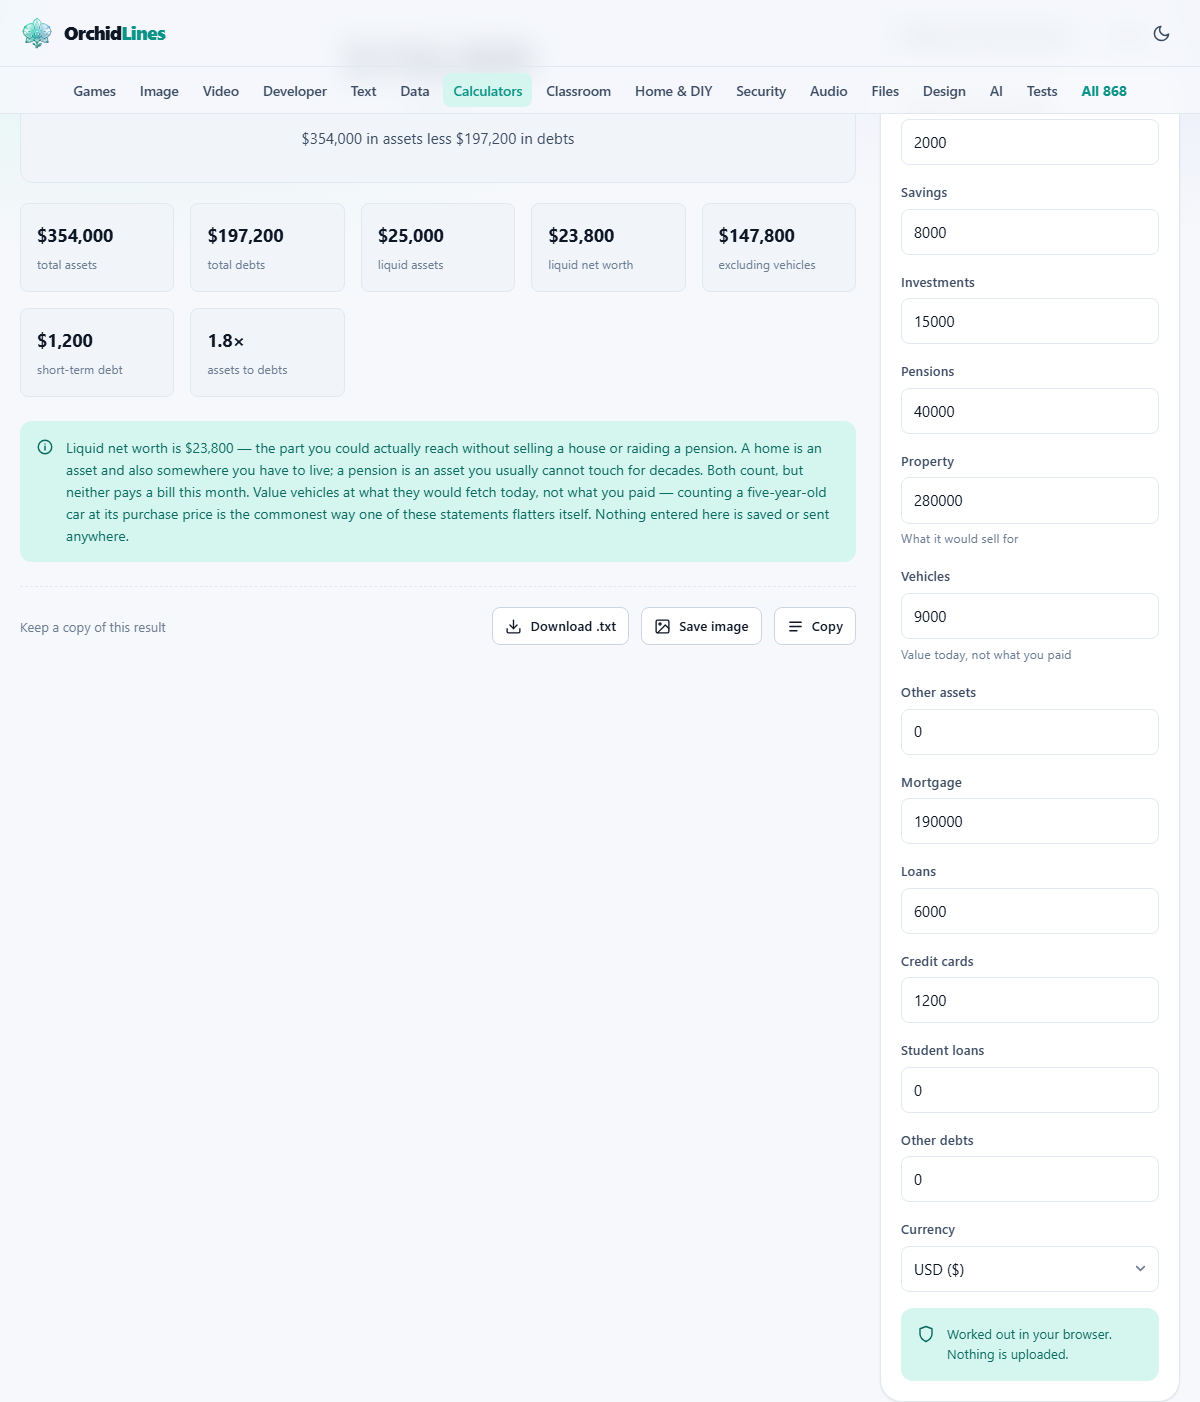
The calculator lists seven categories of assets on the right-hand panel. Cash in current accounts is money you can spend right now, sitting in your everyday bank account. Savings covers money set aside in savings accounts, fixed deposits or any similar pot that earns interest. Investments includes stocks, mutual funds, bonds, ETFs and anything else you hold in a trading or brokerage account. Pensions is the current value of any retirement savings, whether that is an employer-run scheme, a personal pension or a government-linked fund.
Property should be what your home or any other real estate would sell for today, not what you paid for it years ago. Markets change and neighbourhoods shift, so the price you paid five or ten years back is often quite different from the current value. Vehicles should likewise be today's market value. A car loses value from the day it is driven off the lot, and entering the original purchase price instead of the current resale price is the single most common way that a net worth figure ends up looking better than it really is. Other assets is a catch-all for anything that does not fit the other boxes, things like jewellery, art, collectibles or a share in a small business.
Filling in the debt fields
Five categories cover what you owe. Mortgage is the outstanding balance on your home loan, not the monthly payment you make. If you have paid off half of a two hundred thousand mortgage, enter one hundred thousand. Loans covers personal loans, car finance, hire purchase and any other money borrowed from a bank or lender. Credit cards is the total balance across all your cards. Student loans is for education debt, and Other debts is a catch-all for anything else, like money owed to a family member, a medical bill on a payment plan or a buy-now-pay-later balance.
For every debt field, always enter the full amount still owed, not the monthly payment. If you have a car loan with twelve thousand left to pay, enter twelve thousand even though your monthly payment is only three hundred. The calculator works with balances, not with cash flow. Mixing up the two is an easy mistake and one that makes debts look much smaller than they are. A person who enters monthly payments instead of balances could understate their debts by a factor of thirty or more.
What the result tells you
Once all the fields have values, the result appears right away. It shows total assets, total debts and net worth as the difference between them. But the calculator goes further. It also breaks out liquid net worth, which is the part of your wealth you could actually get your hands on quickly.
Liquid net worth typically includes cash, savings and investments. It leaves out property and pensions, because you cannot sell a house overnight and you cannot touch a pension for decades. A person with a large net worth but almost no liquid assets is in a fragile position. One bad month, one unexpected bill, and there is no cash to cover it. The headline number hides this risk entirely, which is why the liquid figure matters so much.
The calculator also shows net worth excluding vehicles, since cars and motorbikes lose value steadily and are not true investments. A Currency dropdown lets you label the result in your local currency.
How to value things honestly
The hardest part of a net worth calculation is not the maths. It is putting honest numbers in the boxes. Property values are easy to inflate. A quick search for similar homes in your area will give a better estimate than your gut feeling or what a neighbour sold for two years ago. Cars can be checked on any used-vehicle pricing site.
Pensions are simpler because the fund usually tells you the current value. Investments can be read straight from a brokerage statement. For debts, log into each account and use the latest balance. The goal is a snapshot of today, not a memory of last year. A net worth figure based on stale numbers gives you false comfort or false alarm, and neither is helpful.
What a negative number means
If your debts exceed your assets, your net worth is negative. This worries people more than it should. A new mortgage almost always pushes the number below zero. The debt is large and the deposit you paid was a big share of your savings, so the balance sheet tips sharply. A recent graduate with student loans and very few assets is in a similar spot. Both situations are normal, expected and temporary for most people.
What matters is the trend over time, not the number on any single day. If the figure moves toward zero and then crosses into positive territory over the years, you are building wealth, even if the starting point looked bad. If the number keeps dropping year after year, something needs to change. Checking once or twice a year gives you enough data to see the direction clearly without getting distracted by daily noise from stock markets or shifting property estimates.
Tracking your net worth over time
A single net worth calculation is a snapshot. It tells you where you stand right now, but the real value comes from repeating it at regular intervals and comparing the results. Once or twice a year is a good pace. More often than that and you are mostly watching stock prices and property estimates bounce around, which tells you nothing about your own behaviour or your own decisions.
Write the total down somewhere after each check. A simple list of dates and figures in a notebook or a spreadsheet is enough. Over several years the pattern shows whether your savings are growing, whether your debts are shrinking, and whether big events like buying a home, changing jobs or paying off a loan moved the needle. The direction matters more than the size of any single number. Someone whose net worth went from minus fifty thousand to minus twenty thousand in three years is making strong progress, even though the number is still negative.
The calculator does not save anything for you, so keeping your own record is the only way to get that long view. Take a note of the total and the liquid figure each time, and the story will tell itself over a few years.
Privacy and where the numbers stay
Financial details are personal, and this calculator treats them that way. Everything runs in your browser. Nothing is uploaded to a server. There is no login, no account and no database storing your figures. The moment you close the page, the numbers are gone. If you want to keep a copy, write them down or use the result as a reference before you leave.
Because the calculation is purely local, you can use it on a shared computer without worrying about leaving a trail. No cookies record the values, no history entry captures what you typed, and no log file is written anywhere. The page starts completely fresh every time it loads, as though it has never been used before.